Tax residency certificate in Poland
A tax residency certificate (certyfikat rezydencji) is a certificate of a taxpayer’s place of residence or registered seat for tax purposes. It is issued by the tax administration of the state in which the taxpayer lives or has its seat. The definition is found in Article 5a(21) of the Personal Income Tax Act of 26 July 1991, the PIT Act, and Article 4a(12) of the Corporate Income Tax Act of 15 February 1992, the CIT Act.
The document is of particular importance for withholding tax. It allows a Polish withholding agent to apply the rate or exemption of a double tax treaty instead of the domestic rate when it pays dividends, interest, royalties or fees for intangible services to a non-resident. Polish residents use it in the reverse situation, when a foreign payer withholds tax on their income. In residence disputes it is one piece of evidence among others.
For anyone paying money abroad, the certificate is the first document in the file. It is not the last. Since 2019 the agent must also exercise due diligence and, for dividends, interest and royalties, check who the beneficial owner of the payment is.
Key points
- Without a certificate the agent applies the statutory rate. In CIT this is 20 percent on interest, royalties and intangible services and 19 percent on dividends (Articles 21(1) and 22(1) CIT Act). In PIT, services, royalties and interest outside Article 30a are taxed at 20 percent (Article 29(1) PIT Act), while dividends and interest under Article 30a(1) PIT Act are taxed at 19 percent. The certificate is a condition of applying a treaty (Article 26(1) CIT Act; Articles 29(2) and 30a(2) PIT Act).
- A certificate without a stated period of validity is honoured by the agent for 12 months from its date of issue (Article 26(1i) CIT Act; Article 41(9a) PIT Act). If the taxpayer changes residence within that period and delivers no new certificate, the taxpayer is liable for the tax not withheld (Article 26(1j) and (1k) CIT Act; Article 41(9b) and (9c) PIT Act). The exception: where the documents held by the agent show the change of seat or residence (Article 26(1l) CIT Act; Article 41(9d) PIT Act).
- Since 1 January 2022 a copy suffices if the information it contains raises no reasonable doubt as to its conformity with the facts (Article 26(1n) CIT Act; Article 41(9e) PIT Act). An electronic certificate issued in that form by a foreign administration is fully valid.
- The certificate confirms residence for the period it covers. It may be obtained after the payment, provided it covers the payment date. It does not replace due diligence (Article 26(1) CIT Act). For passive payments, meaning dividends, interest and royalties, it does not replace the beneficial owner examination either (Article 4a(29) CIT Act). Under the Minister of Finance’s explanatory notes of 3 July 2025 the beneficial owner condition does not apply to intangible services.
- A Polish resident obtains a certificate (form CFR-1) from the head of the tax office within 7 days (Article 306l and Article 306a(5) of the Tax Ordinance). An application through the e-Tax Office portal or the e-US app is free of stamp duty. A paper application or one filed through e-Delivery attracts PLN 17.
- A foreign certificate does not bind the Polish authority in a dispute over where the taxpayer actually lives. Statutory criteria and the tie-breaker rules of the applicable treaty, modelled on Article 4(2) of the OECD Model Convention, decide.
Legal basis and function
Polish income tax statutes require withholding agents to collect a flat-rate tax on amounts paid to non-residents under the headings listed in Articles 21(1) and 22(1) CIT Act and Articles 29(1) and 30a(1) PIT Act. Double tax treaties reduce those rates or allocate the exclusive taxing right to the recipient’s state of residence. The agent may rely on them only after documenting the taxpayer’s seat or residence with a certificate obtained from the taxpayer (Article 26(1) CIT Act; Article 29(2) PIT Act).
The same document conditions the exemptions implementing the EU directives on dividends, interest and royalties paid to associated companies (Article 26(1c) CIT Act). Alongside the certificate the agent must then obtain the taxpayer’s written statement that the conditions of the exemption are met (Article 26(1f) CIT Act). Collection and refund are described in the entry on withholding tax in Poland, the directive exemption in the entry on the participation exemption, and its anti-abuse limits in our article on the anti-abuse clause and the parent-subsidiary dividend exemption.
|
Payment to a non-resident CIT taxpayer |
Statutory rate | Role of the certificate |
| Dividend | 19 percent (Article 22(1) CIT Act) | treaty rate, usually 5 to 15 percent, or directive exemption; see the entry on dividend withholding tax |
| Interest | 20 percent (Article 21(1)(1) CIT Act) | treaty rate, usually 5 to 10 percent, or exemption; see the article on the beneficial owner of interest and the preferential rate |
| Royalties |
20 percent (Article 21(1)(1) CIT Act) |
treaty rate or exemption; disputes over the treaty definition of royalties |
| Intangible services (advisory, advertising, management) | 20 percent (Article 21(1)(2a) CIT Act) | most treaties allocate the taxing right exclusively to the state of residence; see the entry on taxation of intangible services |
| Fees paid to an individual for services, royalties and interest outside Article 30a (Article 29(1) PIT Act) | 20 percent | treaty application requires a certificate (Article 29(2) PIT Act); dividends and interest under Article 30a(1) PIT Act are taxed at 19 percent and the treaty applies once a certificate is produced (Article 30a(2)) |
The concept is defined functionally. What matters is not the name or form of the document. What matters is whether the tax administration of the state of residence issued it and whether it certifies the place of residence or seat for tax purposes. An extract from a commercial register, a VAT registration certificate, a decision assigning a tax identification number or the taxpayer’s own declaration are not certificates. A document issued by a foreign authority needs no apostille or legalisation. It needs a Polish translation if the authority so demands.
Validity, copies and electronic form
The statutes do not say how long a certificate remains current. The rule was introduced by an amendment in force since 4 January 2015: a certificate without a stated period of validity is honoured by the agent for the next 12 months from its date of issue (Article 26(1i) CIT Act; Article 41(9a) PIT Act). This is a rule about how long the agent may rely on the document. It is not a guarantee that the taxpayer’s residence will remain unchanged for a year.
If the taxpayer’s seat or residence changes within that period, the taxpayer must immediately document the new residence with a new certificate (Article 26(1j) CIT Act). If it does not, the taxpayer, not the agent, is liable for tax not withheld or withheld at too low a rate (Article 26(1k) CIT Act). That rule does not operate where the documents held by the agent, for example an invoice or a contract, show the change of seat. From the moment it obtains such a document the agent may no longer rely on the old certificate and is itself liable for the tax (Article 26(1l) CIT Act). A certificate stating a period of validity is applied for that period, even if longer than a year.
Until the end of 2021 the statutes accepted a copy only for intangible services and payments of up to PLN 10,000 a year to one recipient. A wider exception for the epidemic period was provided by Article 31ya of the Act of 2 March 2020 on special measures connected with COVID-19. Since 1 January 2022 a copy suffices in every case, provided the information it contains raises no reasonable doubt as to its conformity with the facts (Article 26(1n) CIT Act; Article 41(9e) PIT Act). In practice this means acceptance of scans and of electronic certificates issued by administrations that no longer use paper.
The channel of delivery is not decisive in itself. In an individual ruling of 23 April 2025 (0114-KDIP2-1.4010.118.2025.1.MR1) the Director of the National Tax Information accepted an Irish certificate issued as a PDF file and passed on by the counterparty. It cautioned, however, that a file downloaded from the payee’s own website carries the risk that its content or form has been altered. The agent should therefore verify the issuing authority, the taxpayer’s details, the period covered and the integrity of the file. For an electronic certificate it also checks whether that form is official in the issuing state. Where doubts exist, it requests the original or confirmation from the issuing authority.
A certificate confirms a past or present state, not a future one. It may therefore be obtained after the payment if it confirms residence on the payment date. An agent that held no certificate on the payment date bears the risk of never receiving one. In that case it is liable for the tax not withheld. The safe practice is to collect the certificate before the first payment of the year and to provide for its renewal in the agent’s due diligence policy. The obligations involved are set out in the article on withholding tax agent obligations.
Certificate for a Polish resident: form CFR-1
A person or company subject to unlimited tax liability in Poland obtains a certificate on application from the head of the tax office (Article 306l Tax Ordinance), on form CFR-1, the template of which is set by a regulation issued under Article 306n. The certificate must be issued without undue delay, no later than within 7 days (Article 306a(5)).
An application filed through the e-Tax Office portal or the e-US app is exempt from stamp duty. The certificate is then issued electronically with the office’s seal. A paper application or one filed through e-Delivery attracts PLN 17 in stamp duty. This is confirmed by the Ministry of Finance’s information on the CFR certificate.
The document states the period it covers. It serves as the basis for the foreign payer to apply the treaty and for recovering tax overpaid abroad. Before using an electronic certificate abroad, check the requirements of the administration or payer in the state concerned; not every jurisdiction accepts a document without a handwritten signature without question. The criteria the authority examines before issuing the certificate (place of residence, centre of vital interests, the 183-day test) are explained in the entry on tax residency in Poland.
The certificate in a residence dispute
A foreign certificate proves that the other state regards the taxpayer as its resident. It does not oblige the Polish authority to treat the taxpayer as a non-resident. If an individual meets the Polish test of a centre of vital interests or presence exceeding 183 days (Article 3(1a) PIT Act), a residence conflict arises.
The conflict is resolved by the tie-breaker rules of the applicable double tax treaty, as modified where relevant by the Multilateral Instrument. The typical sequence, modelled on Article 4(2) of the OECD Model Convention, is permanent home, closer personal and economic relations, habitual abode, nationality and, failing all else, mutual agreement of the competent authorities. The wording of the particular treaty may differ. In such cases the authorities examine where the family lives, real property, bank accounts, professional activity and travel records. The certificate is one piece of evidence among others. The practical side of a move abroad, including audits that follow it, is covered in our guide to changing tax residency.
For companies the certificate gives no protection against the charge that effective management is exercised from Poland (Article 3(1) CIT Act) or against the controlled foreign company rules. A company holding a certificate from a low-tax state but without an office, staff and decisions taken on the spot may fail the beneficial owner test. The explanatory notes of 3 July 2025 require an assessment adequate to the recipient’s type of activity, provide for lower substance requirements for holding companies and accept, under specified conditions, shared personnel and assets. A single feature does not decide the matter, but it triggers the agent’s duty of deeper verification. The beneficial ownership test for dividends is analysed in our article on beneficial ownership and dividend distributions.
Due diligence and the pay and refund mechanism
Since 2019 the certificate has been a necessary but insufficient condition. The agent must exercise due diligence in verifying the conditions for a treaty rate or exemption, taking into account the nature and scale of its activity and its links with the taxpayer (Article 26(1) CIT Act). The beneficial owner examination concerns passive payments: dividends, interest and royalties, also where the treaty contains no express beneficial owner clause. For intangible services the verification does not include that condition. That follows from the explanatory notes of 3 July 2025.
For dividends, interest and royalties paid to a related entity that is not a Polish resident, the pay and refund mechanism applies. Where the total paid to the same taxpayer exceeds PLN 2,000,000 in the agent’s tax year, the agent as a rule withholds tax at the statutory rate on the excess, and the taxpayer or the agent then applies for a refund (Article 26(2e) and (2eb) CIT Act). The mechanism does not cover intangible services under Article 21(1)(2a).
Withholding may be avoided in two ways. The first is the agent’s WH-OSC statement, signed by the head of the entity or, where the management body has several members, by a designated member of that body; a proxy may not sign it (Article 26(7a) and (7b) CIT Act). The second is an opinion on the application of preferences issued by the tax authority (Article 26b CIT Act). In both procedures the certificate remains the source document. Alongside it the agent collects evidence of the recipient’s genuine activity and beneficial owner status, including whether the recipient recognises the income in its state of residence.
What to check before applying a treaty rate
- Whether the document comes from the tax administration of the state of residence and certifies residence or seat for tax purposes. A commercial register extract or a VAT number is not enough.
- Whether the certificate covers the payment date: the period stated in the document or, failing that, 12 months from issue. Whether other documents show a change of seat (Article 26(1l) CIT Act).
- Whether the provenance and integrity of a copy can be verified (issuing authority, taxpayer’s details, period, official form in the issuing state). Where doubts exist, request the original or confirmation from the issuing authority.
- For dividends, interest and royalties: whether the recipient is the beneficial owner and carries on genuine activity. For related entities, due diligence documentation, and above PLN 2,000,000 a year to the same taxpayer the WH-OSC statement or an opinion on the application of preferences.
- Whether the treaty with the state concerned provides a reduced rate for this category of payment and contains no limitation on benefits clause; see the entry on double taxation agreements.
- Whether the agent filed the IFT-2R or IFT-1R information after the payment and whether the certificate is retained until the limitation period expires.
What legal assistance looks like in such a case
Withholding tax disputes usually arise years later, when the authority reviews payments to foreign recipients and asks for the documents as they stood on the payment date. What counts then is what the agent gathered beforehand: a certificate covering the payment date, statements, evidence of the recipient’s genuine activity and a record of how the verification was carried out. An adviser helps to turn that documentation into a procedure that will withstand an audit, and to judge when it is safer to withhold and claim a refund, and when to file a WH-OSC statement or apply for an opinion.
On the other side are individuals who have left Poland and hold a foreign certificate, yet still receive a request from the tax office. In those cases the certificate is the beginning of the argument, not its end. Counsel builds the evidence of the centre of vital interests and applies the tie-breaker rules of the relevant treaty.
Skarbiec Law Firm advises withholding agents on withholding tax compliance and individuals on changing tax residency, including disputes in which the authority challenges a foreign certificate.
Counterparts in other jurisdictions
Each state issues its own residence certificates. In Germany it is the Ansässigkeitsbescheinigung issued by the Finanzamt on the other state’s form or its own. In the United Kingdom the certificate of residence is issued by HMRC. In the United States Form 6166 is issued by the IRS on an application on Form 8802. What they share is that the document confirms status under the law of the issuing state and does not resolve a residence conflict; that remains a treaty matter. Poland stands out for its extensive beneficial owner practice and for the pay and refund mechanism, which has no counterpart in many jurisdictions.
Frequently asked questions
What is a tax residency certificate?
A certificate of a taxpayer’s place of residence or seat for tax purposes issued by the tax administration of the state of residence (Article 5a(21) PIT Act, Article 4a(12) CIT Act). It allows a withholding agent to apply a treaty rate instead of the domestic rate.
How long is a certificate of residence valid in Poland?
For the period stated in the document. If none is stated, the agent may rely on it for 12 months from its date of issue (Article 26(1i) CIT Act, Article 41(9a) PIT Act), unless the documents it holds show a change of the taxpayer’s seat or residence. The certificate must cover the date of payment.
Is a copy of the certificate sufficient?
Yes, since 1 January 2022 in every case, provided the information in the copy raises no reasonable doubt as to its conformity with the facts (Article 26(1n) CIT Act, Article 41(9e) PIT Act). The agent should be able to verify the issuing authority, the taxpayer’s details, the period and the integrity of the document.
How do I obtain a Polish certificate of residence?
By filing form CFR-1 with the head of the tax office. Through the e-Tax Office portal it is free of stamp duty; on paper or through e-Delivery the stamp duty is PLN 17. The certificate is issued within 7 days (Article 306l and Article 306a(5) Tax Ordinance).
Does the certificate release the withholding agent from liability?
Not entirely. The agent must exercise due diligence and, for dividends, interest and royalties, examine beneficial owner status (Article 26(1) CIT Act). If, however, the taxpayer changed residence during the certificate’s validity and delivered no new certificate, the taxpayer is liable for the tax not withheld (Article 26(1k) CIT Act), unless the agent knew of the change from other documents it held (Article 26(1l) CIT Act).
Does a foreign certificate protect me from being treated as a Polish resident?
No. The Polish authority examines the criteria of Article 3(1a) PIT Act and a residence conflict is resolved by the tie-breaker rules of the applicable treaty. The certificate is one piece of evidence, not a ruling.
Related entries
- Tax residency in Poland
- Withholding tax in Poland
- Dividend withholding tax
- Double taxation agreements
- Taxation of intangible services
- Taxation of foreign source income
- Related parties and affiliated entities
Legal status as of 1 November 2026.
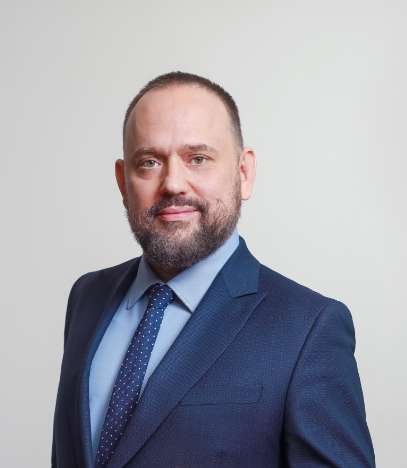
Robert Nogacki is a Polish attorney at law (radca prawny), the founder and managing partner of Kancelaria Prawna Skarbiec (Skarbiec Law Firm), which has operated continuously since 2006.
The law is equal for everyone, but the parties rarely are: on one side stands an organization with time, money, and lawyers, on the other a person with one business, one nest egg, and one life.
Clients rarely come to him with a legal problem. They come with a problem that also has a legal side: an audit that began with a single invoice, money entrusted to someone who has disappeared, a company that has to be passed on before it is too late. Most such matters are decided long before the first letter is written, in decisions made without asking and in deadlines nobody remembered. So he begins by asking how the client got here, not what the client should have done.
He advises entrepreneurs and families from more than a dozen countries, including those whose accounts the tax office has just seized and who do not know what to do tomorrow morning. He defends them in tax audits, customs and fiscal inspections, disputes with the tax authorities, and criminal tax proceedings. He represents victims of investment fraud and Ponzi schemes. He helps families set up family foundations and plan succession, so that a life’s work outlasts a single generation.
Not every case can be won. Every case can be run so that the client knows where they stand. Since 2006 he has represented the victims in the WGI case (Warszawska Grupa Inwestycyjna, the Warsaw Investment Group), one of the longest criminal cases in the history of the Polish financial market, because some things must not be left half finished, even when they take two decades. In the case of the collapsed cryptocurrency exchange Zonda (Zondacrypto, operated by BB Trade Estonia OÜ), he represents several hundred victims in the criminal investigation conducted by Poland’s National Prosecutor’s Office and in the Estonian bankruptcy proceedings.
Kancelaria Prawna Skarbiec is listed in the rankings of Poland’s largest tax advisory firms published by Dziennik Gazeta Prawna and Rzeczpospolita, and it is a four-time recipient (2015 to 2018) of the European Medal awarded by the Business Centre Club and the European Economic and Social Committee. Robert Nogacki publishes regularly, in the press and on the firm’s website, for people who have a problem rather than a law degree, because a legal opinion the client cannot understand protects only the lawyer.
He believes that the best legal advice is the kind that means the client never has to appear in court.